Every year, thousands of Americans apply for a personal loan or mortgage within days of deciding they need one — and then get quoted an interest rate that feels like a punishment. The uncomfortable truth is that the rate you are offered is rarely about the lender's mood; it is almost entirely about the three-digit number on your credit report at the moment they pull it. The good news is that this number is not a life sentence. With six to twelve weeks of deliberate effort, most people can move their score meaningfully upward before signing anything, and every point you gain is money saved for years.
The first step is simply knowing where you stand. You are entitled to free weekly credit reports from all three major bureaus, and checking your own report never hurts your score because it counts as a soft inquiry. Print them out, sit down with a highlighter, and mark every account, balance and late payment listed. About one in five reports contains at least one error — a paid account still showing a balance, a duplicate collection, or an address that isn't yours — and every one of those errors can be dragging your score down for no reason at all.
Once you have identified inaccuracies, dispute them in writing with the bureau that reports them, and send the same dispute to the data furnisher, such as the collection agency or card issuer. The law requires bureaus to investigate within thirty days, and in our experience roughly two-thirds of disputed errors are corrected or deleted entirely. We have watched clients gain forty to sixty points from a single corrected collection entry, with no other change to their financial behavior whatsoever.
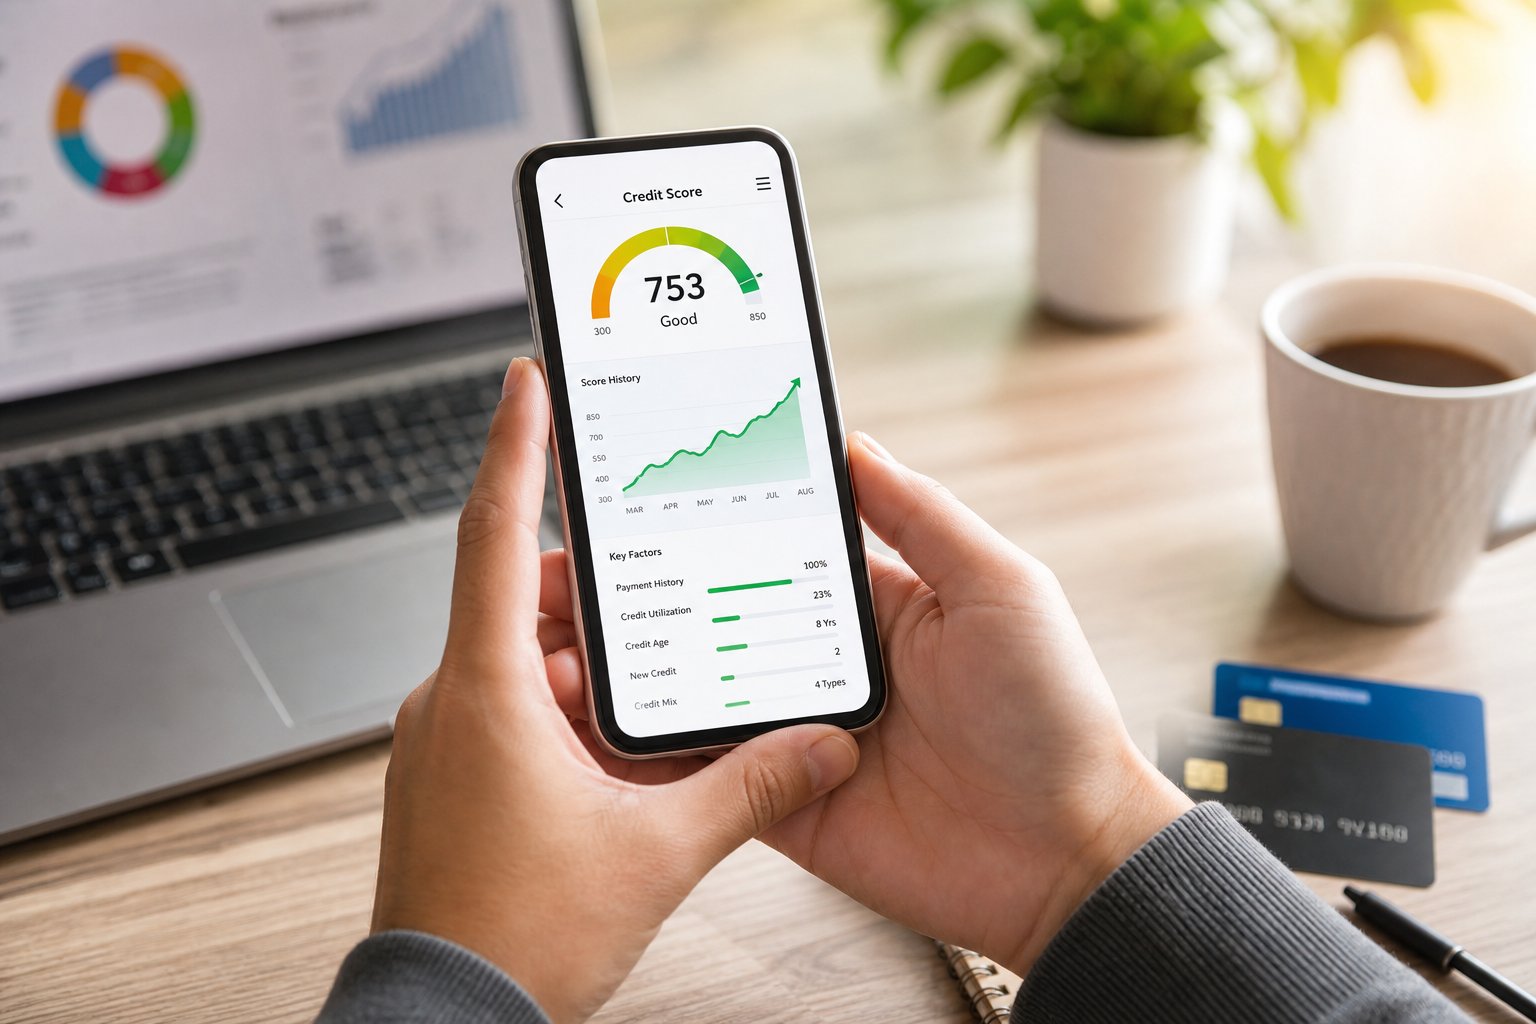
After cleanup comes utilization, the factor you can move fastest. Credit scoring models reward you heavily for using less than thirty percent of each card's limit, and reward you even more for staying under ten percent. If you carry a four-thousand-dollar balance on a ten-thousand-dollar limit card, you are at forty percent utilization and paying for it in points. Paying that balance down to two thousand five hundred — before the statement closing date, not merely before the due date — can produce a visible score jump within a single billing cycle.
Next, protect your payment history, which remains the single largest component of your score. One thirty-day late payment can cost eighty points or more and stays visible for years. Set up automatic minimum payments on every account, even ones you pay manually, so a forgotten due date can never ambush you again. If you are currently behind, bring the account current as quickly as possible and call the creditor to ask about goodwill adjustments — many lenders will remove a first-time late mark for a long-standing customer who simply asks.
Equally important is what you do not do in the months before a loan application. Each new credit application triggers a hard inquiry, and opening new accounts lowers your average age of accounts, so a store card opened in March can quietly cost you a better mortgage rate in June. Likewise, closing an old paid-off card reduces your total available credit and raises your utilization ratio. In the ninety days before applying for financing, the best strategy is usually boring: no new cards, no closed cards, no co-signing, and no large unexplained deposits moving through your bank accounts.
If your file is thin rather than damaged — common for young borrowers and new residents — a credit-builder loan is one of the fastest legitimate ways to add positive history. These small installment loans are held in a savings account while you make on-time monthly payments, which are reported to all three bureaus, and the funds are released to you at the end. Combined with becoming an authorized user on a family member's old, well-managed card, thin-file clients of ours routinely cross the seven-hundred threshold within a year.
Finally, time your actual loan applications intelligently. Scoring models treat multiple mortgage or auto loan inquiries made within a short shopping window as a single inquiry, so rate-shopping aggressively for two weeks is smart, while applying sporadically over three months is not. When your score has climbed into the lender's better pricing tier, apply confidently — and keep the habits that got you there, because the same discipline that earned your rate is what will protect it for the next big purchase.
Improving your credit score is not magic and it does not require a finance degree; it requires accuracy, low utilization, perfect payment timing and a little patience. Start with your free reports today, dispute what is wrong, pay down what you can, and freeze new applications until you are ready. If you would like a professional pair of eyes on your report before you apply, our advisors at Finance Revenue Boost review tri-bureau reports for free and will map the fastest legal route to your best possible rate.
Key Takeaways
- Pull all three free credit reports and dispute every error in writing.
- Keep utilization under 30% per card — under 10% is even better.
- Automate minimum payments so a missed due date never happens.
- Avoid new credit and closed accounts for 90 days before applying.
- Use credit-builder loans to add positive history to thin files.
- Cluster rate-shopping inquiries into a single two-week window.